Sunday, November 2, 2025

Global Home Decor Market Research Report 2025

What is Global Home Decor Market?

The Global Home Decor Market is a vast and dynamic industry that encompasses a wide range of products designed to enhance the aesthetic appeal and functionality of living spaces. This market includes everything from furniture and textiles to flooring and lighting, catering to diverse consumer preferences and styles. As people increasingly prioritize creating comfortable and visually pleasing environments, the demand for home decor products continues to rise. The market is driven by factors such as urbanization, rising disposable incomes, and a growing interest in interior design. Additionally, the influence of social media and home improvement shows has heightened consumer awareness and aspirations, further fueling market growth. The Global Home Decor Market is characterized by a mix of established brands and emerging players, offering a variety of products that cater to different tastes and budgets. As sustainability becomes a key consideration for consumers, eco-friendly and ethically sourced products are gaining popularity, prompting manufacturers to innovate and adapt. Overall, the Global Home Decor Market is a vibrant and evolving sector that reflects changing lifestyles and consumer preferences, offering endless possibilities for personal expression and creativity in home design.
Home Decor Market

Home Furniture, Rugs, Bath Textiles, Bed Textiles, Kitchen and Dining Textiles, Tiles, Wood & Laminate Flooring, Vinyl & Rubber Flooring, Lighting, Others in the Global Home Decor Market:

Home furniture is a cornerstone of the Global Home Decor Market, encompassing a wide array of products such as sofas, chairs, tables, and storage units. These items are essential for both functionality and style, providing comfort and utility while enhancing the aesthetic appeal of living spaces. Rugs, another key component, add warmth and texture to rooms, offering a simple yet effective way to transform the look and feel of a space. Bath textiles, including towels and shower curtains, contribute to the comfort and hygiene of bathrooms, while bed textiles like sheets, pillowcases, and duvets play a crucial role in ensuring a good night's sleep. Kitchen and dining textiles, such as tablecloths and napkins, add a touch of elegance to meal times, making everyday dining experiences more enjoyable. Tiles are a versatile element in home decor, used in bathrooms, kitchens, and flooring to provide durability and style. Wood and laminate flooring offer a classic and timeless look, while vinyl and rubber flooring provide practical and cost-effective solutions for various areas of the home. Lighting is another critical aspect of home decor, with options ranging from chandeliers and pendant lights to floor lamps and wall sconces, each contributing to the ambiance and functionality of a space. Other elements in the Global Home Decor Market include decorative accessories, wall art, and window treatments, all of which allow homeowners to express their personal style and create a cohesive look throughout their homes. The market is continually evolving, with trends such as minimalism, maximalism, and sustainable design influencing consumer choices and driving innovation among manufacturers. As a result, the Global Home Decor Market offers a diverse range of products that cater to different tastes, preferences, and budgets, making it an exciting and dynamic industry.

Indoor, Outdoor, Others in the Global Home Decor Market:

The usage of products from the Global Home Decor Market extends across various areas, including indoor, outdoor, and other spaces, each with its unique requirements and opportunities for creativity. Indoor spaces, such as living rooms, bedrooms, kitchens, and bathrooms, are the primary focus of home decor, with products designed to enhance comfort, functionality, and aesthetic appeal. In living rooms, furniture like sofas, coffee tables, and entertainment units create a welcoming environment for relaxation and socializing. Bedrooms benefit from cozy textiles, stylish furniture, and calming color schemes that promote rest and rejuvenation. Kitchens and dining areas are enhanced with functional yet stylish furniture, textiles, and lighting that make cooking and dining experiences more enjoyable. Bathrooms are transformed with elegant fixtures, textiles, and accessories that combine practicality with luxury. Outdoor spaces, such as gardens, patios, and balconies, are increasingly becoming extensions of indoor living areas, with decor products designed to withstand the elements while providing comfort and style. Outdoor furniture, lighting, and textiles create inviting spaces for relaxation and entertainment, while decorative elements like planters, sculptures, and water features add visual interest and personality. Other areas, such as home offices, entryways, and utility rooms, also benefit from thoughtful decor choices that enhance functionality and aesthetics. Home offices, for example, require ergonomic furniture, adequate lighting, and organizational solutions to create a productive and inspiring work environment. Entryways set the tone for the rest of the home, with decor elements like rugs, lighting, and storage solutions that create a welcoming and organized space. Utility rooms, often overlooked, can be transformed with practical and stylish storage solutions, lighting, and textiles that make everyday tasks more efficient and enjoyable. Overall, the Global Home Decor Market offers a wealth of products and solutions that cater to the diverse needs and preferences of homeowners, allowing them to create personalized and harmonious living environments both indoors and outdoors.

Global Home Decor Market Outlook:

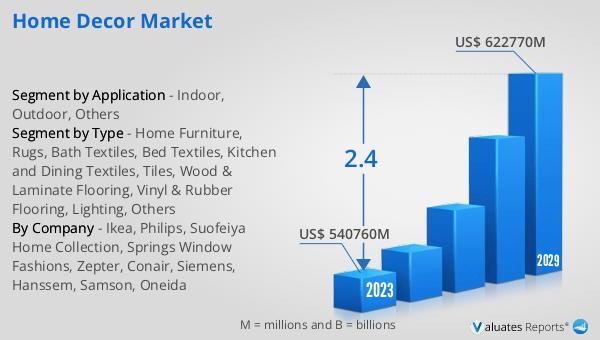
The global market for home decor was valued at approximately $552.35 billion in 2024, showcasing its significant economic impact and widespread consumer interest. This market is projected to grow steadily, reaching an estimated size of $649.75 billion by 2031. This growth trajectory reflects a compound annual growth rate (CAGR) of 2.4% over the forecast period. The steady increase in market size underscores the ongoing demand for home decor products as consumers continue to invest in enhancing their living spaces. Factors contributing to this growth include rising disposable incomes, urbanization, and a growing interest in interior design and home improvement. Additionally, the influence of social media and home renovation shows has heightened consumer awareness and aspirations, driving demand for stylish and functional home decor products. As the market evolves, manufacturers and retailers are adapting to changing consumer preferences, offering a diverse range of products that cater to different tastes, styles, and budgets. The emphasis on sustainability and eco-friendly products is also shaping the market, with consumers increasingly seeking out environmentally responsible options. Overall, the global home decor market is poised for continued growth, driven by a combination of economic, social, and cultural factors that influence consumer behavior and preferences.


Report Metric Details
Report Name Home Decor Market
Accounted market size in year US$ 552350 million
Forecasted market size in 2031 US$ 649750 million
CAGR 2.4%
Base Year year
Forecasted years 2025 - 2031
Segment by Type
  • Home Furniture
  • Rugs
  • Bath Textiles
  • Bed Textiles
  • Kitchen and Dining Textiles
  • Tiles
  • Wood & Laminate Flooring
  • Vinyl & Rubber Flooring
  • Lighting
  • Others
Segment by Application
  • Indoor
  • Outdoor
  • Others
Consumption by Region
  • North America (United States, Canada)
  • Europe (Germany, France, UK, Italy, Russia)
  • Asia-Pacific (China, Japan, South Korea, Taiwan)
  • Southeast Asia (India)
  • Latin America (Mexico, Brazil)
By Company Ikea, Philips, Suofeiya Home Collection, Springs Window Fashions, Zepter, Conair, Siemens, Hanssem, Samson, Oneida
Forecast units USD million in value
Report coverage Revenue and volume forecast, company share, competitive landscape, growth factors and trends

Global Hyaluronic Acid Products Market Research Report 2025

What is Global Hyaluronic Acid Products Market?

The Global Hyaluronic Acid Products Market is a dynamic and rapidly evolving sector that focuses on the production and distribution of hyaluronic acid-based products. Hyaluronic acid is a naturally occurring substance in the human body, primarily found in connective tissues, skin, and eyes. It plays a crucial role in retaining moisture, providing lubrication, and promoting tissue repair. The market for hyaluronic acid products has been expanding due to its wide range of applications in various industries, including cosmetics, pharmaceuticals, and medical devices. In the cosmetics industry, hyaluronic acid is highly valued for its hydrating properties, making it a popular ingredient in skincare products such as moisturizers, serums, and dermal fillers. In the medical field, it is used in treatments for osteoarthritis, ophthalmic surgeries, and as a component in injectable products for joint pain relief. The increasing awareness of the benefits of hyaluronic acid, coupled with advancements in technology and research, has led to a surge in demand for these products globally. As consumers become more health-conscious and seek effective solutions for skin and joint health, the Global Hyaluronic Acid Products Market is poised for continued growth and innovation.

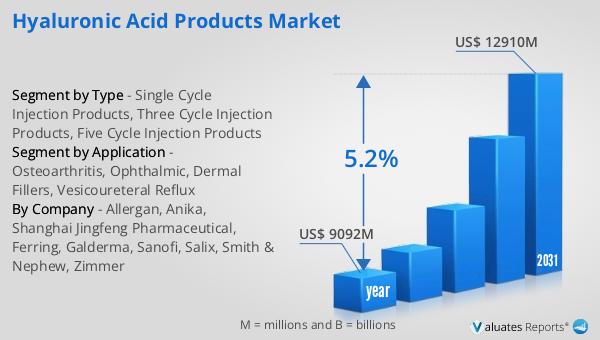
Hyaluronic Acid Products Market

Single Cycle Injection Products, Three Cycle Injection Products, Five Cycle Injection Products in the Global Hyaluronic Acid Products Market:

In the Global Hyaluronic Acid Products Market, there are various types of injection products designed to cater to different medical needs and treatment durations. Single Cycle Injection Products are typically used for short-term relief and are often preferred for their convenience and quick results. These products are administered in a single dose, providing immediate relief from symptoms such as joint pain or skin dehydration. They are particularly popular in the treatment of osteoarthritis, where patients seek rapid alleviation of pain and improved joint function. The ease of administration and minimal discomfort associated with single injections make them an attractive option for both patients and healthcare providers. On the other hand, Three Cycle Injection Products are designed for more sustained relief and are administered over a series of three injections. This approach allows for a gradual buildup of hyaluronic acid in the targeted area, providing longer-lasting effects compared to single injections. Three cycle injections are often used in cases where patients require ongoing treatment to manage chronic conditions or maintain skin hydration over an extended period. The repeated administration ensures a consistent supply of hyaluronic acid, promoting better tissue repair and moisture retention. Five Cycle Injection Products, as the name suggests, involve a series of five injections and are typically used for long-term treatment plans. These products are ideal for patients with severe or persistent conditions that require continuous management. The extended treatment cycle allows for a more comprehensive approach to addressing underlying issues, such as joint degeneration or severe skin dryness. By providing a steady supply of hyaluronic acid over multiple sessions, five cycle injections help to maintain optimal levels of hydration and lubrication in the affected areas. This approach is particularly beneficial for patients with advanced osteoarthritis or those undergoing intensive skincare regimens. The choice between single, three, or five cycle injection products depends on various factors, including the severity of the condition, patient preferences, and the desired duration of relief. Healthcare providers play a crucial role in determining the most appropriate treatment plan based on individual patient needs and medical history. As the Global Hyaluronic Acid Products Market continues to evolve, manufacturers are focusing on developing innovative injection products that offer improved efficacy, safety, and patient comfort. Advances in formulation technology and delivery systems are paving the way for more targeted and personalized treatment options, further enhancing the appeal of hyaluronic acid injections in the medical and cosmetic fields.

Osteoarthritis, Ophthalmic, Dermal Fillers, Vesicoureteral Reflux in the Global Hyaluronic Acid Products Market:

The Global Hyaluronic Acid Products Market finds extensive usage in several key areas, including osteoarthritis, ophthalmic applications, dermal fillers, and vesicoureteral reflux. In the treatment of osteoarthritis, hyaluronic acid is used as an injectable therapy to alleviate joint pain and improve mobility. It acts as a lubricant and shock absorber in the joints, reducing friction and inflammation. Patients with osteoarthritis often experience significant relief from pain and stiffness after receiving hyaluronic acid injections, making it a popular choice for managing this chronic condition. In ophthalmic applications, hyaluronic acid is used in eye surgeries and as a component in eye drops. Its viscoelastic properties make it ideal for maintaining eye shape and protecting delicate tissues during surgical procedures. Hyaluronic acid-based eye drops are also used to relieve dry eye symptoms, providing long-lasting hydration and comfort. In the cosmetic industry, hyaluronic acid is widely used in dermal fillers to enhance facial volume and reduce the appearance of wrinkles and fine lines. Its ability to retain moisture and promote collagen production makes it an effective solution for achieving a youthful and rejuvenated appearance. Dermal fillers containing hyaluronic acid are minimally invasive and offer immediate results, making them a popular choice for individuals seeking non-surgical cosmetic enhancements. Additionally, hyaluronic acid is used in the treatment of vesicoureteral reflux, a condition where urine flows backward from the bladder to the kidneys. In this context, hyaluronic acid is used as a bulking agent to strengthen the bladder wall and prevent reflux. The versatility and effectiveness of hyaluronic acid in these diverse applications highlight its importance in the medical and cosmetic fields. As research continues to uncover new benefits and applications of hyaluronic acid, its usage is expected to expand further, driving growth in the Global Hyaluronic Acid Products Market.

Global Hyaluronic Acid Products Market Outlook:

The global market for Hyaluronic Acid Products was valued at approximately $9,092 million in 2024. It is anticipated to grow significantly, reaching an estimated size of $12,910 million by 2031. This growth trajectory represents a compound annual growth rate (CAGR) of 5.2% over the forecast period. The increasing demand for hyaluronic acid products across various industries, including cosmetics, pharmaceuticals, and medical devices, is a key driver of this market expansion. Consumers are becoming more aware of the benefits of hyaluronic acid, such as its hydrating and anti-aging properties, leading to a surge in demand for skincare products and dermal fillers. In the medical field, the use of hyaluronic acid in treatments for osteoarthritis, ophthalmic surgeries, and other medical conditions is also contributing to market growth. The rising prevalence of chronic diseases and the growing aging population are further fueling the demand for hyaluronic acid-based therapies. Additionally, advancements in technology and research are leading to the development of innovative hyaluronic acid products with improved efficacy and safety profiles. As a result, the Global Hyaluronic Acid Products Market is poised for continued growth and innovation, offering numerous opportunities for manufacturers and stakeholders in the industry.


Report Metric Details
Report Name Hyaluronic Acid Products Market
Accounted market size in year US$ 9092 million
Forecasted market size in 2031 US$ 12910 million
CAGR 5.2%
Base Year year
Forecasted years 2025 - 2031
Segment by Type
  • Single Cycle Injection Products
  • Three Cycle Injection Products
  • Five Cycle Injection Products
Segment by Application
  • Osteoarthritis
  • Ophthalmic
  • Dermal Fillers
  • Vesicoureteral Reflux
Consumption by Region
  • North America (United States, Canada)
  • Europe (Germany, France, UK, Italy, Russia)
  • Asia-Pacific (China, Japan, South Korea, Taiwan)
  • Southeast Asia (India)
  • Latin America (Mexico, Brazil)
By Company Allergan, Anika, Shanghai Jingfeng Pharmaceutical, Ferring, Galderma, Sanofi, Salix, Smith & Nephew, Zimmer
Forecast units USD million in value
Report coverage Revenue and volume forecast, company share, competitive landscape, growth factors and trends

Global Diabetic Macular Edema Drug Market Research Report 2025

What is Global Diabetic Macular Edema Drug Market?

The Global Diabetic Macular Edema Drug Market is a specialized segment within the broader pharmaceutical industry, focusing on treatments for diabetic macular edema (DME), a condition that affects the eyes of individuals with diabetes. DME occurs when fluid accumulates in the macula, the central part of the retina, leading to vision impairment or loss. The market for these drugs is driven by the increasing prevalence of diabetes worldwide, which in turn raises the incidence of DME. As the global population ages and lifestyles change, the number of people affected by diabetes and its complications, such as DME, is expected to rise. This market includes a variety of treatment options, such as anti-VEGF (vascular endothelial growth factor) therapies, corticosteroids, and other emerging treatments. Pharmaceutical companies are investing heavily in research and development to create more effective and safer drugs to manage this condition. The market is characterized by intense competition, with numerous players striving to develop innovative solutions to improve patient outcomes. As awareness of DME and its impact on quality of life grows, the demand for effective treatments is likely to increase, making this a dynamic and evolving market.

Diabetic Macular Edema Drug Market

Intravitreal Injections, Intravitreal Implants in the Global Diabetic Macular Edema Drug Market:

Intravitreal injections and intravitreal implants are two critical methods of delivering medication directly into the eye to treat diabetic macular edema (DME). Intravitreal injections involve administering drugs directly into the vitreous humor, the gel-like substance inside the eye. This method ensures that the medication reaches the retina quickly and in high concentrations, which is crucial for treating conditions like DME. The most common drugs delivered via intravitreal injections are anti-VEGF agents and corticosteroids. Anti-VEGF drugs work by inhibiting the growth of abnormal blood vessels and reducing fluid leakage, which are key contributors to DME. Corticosteroids, on the other hand, help reduce inflammation and swelling in the retina. The procedure for intravitreal injections is relatively quick and is usually performed in an outpatient setting. Patients may experience mild discomfort during the injection, but serious complications are rare when performed by a skilled ophthalmologist. Intravitreal implants, on the other hand, are tiny devices placed inside the eye that slowly release medication over an extended period. These implants are particularly beneficial for patients who require long-term treatment, as they reduce the need for frequent injections. The implants can deliver a steady dose of medication, ensuring consistent therapeutic effects. One of the most well-known intravitreal implants is the dexamethasone implant, which releases corticosteroids to manage inflammation and edema. The choice between intravitreal injections and implants depends on various factors, including the severity of the condition, patient preference, and the specific drug being used. Both methods have their advantages and limitations, and the decision is usually made in consultation with an ophthalmologist. As research continues, new drugs and delivery methods are being developed to improve the efficacy and safety of treatments for DME. The Global Diabetic Macular Edema Drug Market is witnessing significant advancements in this area, with companies exploring novel drug formulations and delivery systems to enhance patient outcomes. The development of biodegradable implants and sustained-release formulations are some of the innovations being pursued to address the challenges associated with current treatment options. These advancements aim to improve patient compliance, reduce the frequency of treatments, and minimize side effects. As the market evolves, the focus remains on providing effective and convenient solutions for managing DME, ultimately improving the quality of life for patients affected by this condition.

Anti-VEGF, Corticosteroids, Others in the Global Diabetic Macular Edema Drug Market:

The Global Diabetic Macular Edema Drug Market encompasses a range of treatment options, with anti-VEGF therapies, corticosteroids, and other emerging treatments playing significant roles. Anti-VEGF therapies are among the most widely used treatments for DME. These drugs work by inhibiting the action of vascular endothelial growth factor (VEGF), a protein that promotes the growth of abnormal blood vessels and increases vascular permeability. By blocking VEGF, these drugs help reduce fluid leakage and swelling in the retina, thereby improving vision. Common anti-VEGF drugs used in the treatment of DME include ranibizumab, aflibercept, and bevacizumab. These medications are typically administered via intravitreal injections, and their efficacy in improving visual acuity and reducing retinal thickness has been well-documented in clinical trials. Corticosteroids are another important class of drugs used in the management of DME. These medications help reduce inflammation and edema in the retina, which are key contributors to vision impairment in DME patients. Corticosteroids can be administered as intravitreal injections or implants, with the latter offering the advantage of sustained drug release over an extended period. Dexamethasone and fluocinolone acetonide are examples of corticosteroids used in the treatment of DME. While corticosteroids are effective in reducing retinal swelling, they are associated with potential side effects such as increased intraocular pressure and cataract formation, which need to be carefully monitored. In addition to anti-VEGF therapies and corticosteroids, the Global Diabetic Macular Edema Drug Market is witnessing the development of other innovative treatments. These include novel drug formulations, combination therapies, and gene therapies aimed at providing more effective and personalized treatment options for DME patients. Combination therapies, which involve the use of multiple drugs with different mechanisms of action, are being explored to enhance treatment efficacy and reduce the frequency of injections. Gene therapies, although still in the experimental stage, hold promise for providing long-term solutions by targeting the underlying genetic causes of DME. As the market continues to evolve, the focus remains on improving patient outcomes and quality of life through the development of safer and more effective treatments. The increasing understanding of the pathophysiology of DME and advancements in drug delivery technologies are driving innovation in this field, offering hope for better management of this challenging condition.

Global Diabetic Macular Edema Drug Market Outlook:

The outlook for the Global Diabetic Macular Edema Drug Market can be contextualized within the broader pharmaceutical industry trends. In 2022, the global pharmaceutical market was valued at approximately 1,475 billion USD, with an anticipated compound annual growth rate (CAGR) of 5% over the next six years. This growth is indicative of the increasing demand for pharmaceutical products, driven by factors such as the rising prevalence of chronic diseases, advancements in drug development, and expanding healthcare access in emerging markets. Within this context, the chemical drug market, a significant component of the pharmaceutical industry, has shown substantial growth. From 2018 to 2022, the chemical drug market expanded from 1,005 billion USD to 1,094 billion USD. This growth reflects the ongoing innovation and development of new chemical entities and formulations to address a wide range of medical conditions, including diabetic macular edema. The increasing focus on personalized medicine and targeted therapies is also contributing to the growth of the chemical drug market. As pharmaceutical companies continue to invest in research and development, the introduction of novel drugs and treatment modalities is expected to drive further growth in the market. The Global Diabetic Macular Edema Drug Market, as a part of this broader industry, is poised to benefit from these trends, with ongoing advancements in drug delivery technologies and the development of more effective treatments for DME. The market's growth is supported by the increasing prevalence of diabetes and its complications, as well as the growing awareness of the impact of DME on patients' quality of life. As the market evolves, the focus remains on improving patient outcomes through the development of innovative and effective treatment options.


Report Metric Details
Report Name Diabetic Macular Edema Drug Market
CAGR 5%
Segment by Type
  • Intravitreal Injections
  • Intravitreal Implants
Segment by Application
  • Anti-VEGF
  • Corticosteroids
  • Others
Consumption by Region
  • North America (United States, Canada)
  • Europe (Germany, France, UK, Italy, Russia)
  • Asia-Pacific (China, Japan, South Korea, Taiwan)
  • Southeast Asia (India)
  • Latin America (Mexico, Brazil)
By Company Novartis, Bayer, Allergan, Hoffman-La Roche, Alimera, Valeant
Forecast units USD million in value
Report coverage Revenue and volume forecast, company share, competitive landscape, growth factors and trends

Global Disposable Cups Market Research Report 2025

What is Global Disposable Cups Market?

The Global Disposable Cups Market refers to the worldwide industry involved in the production, distribution, and consumption of cups that are designed for single-use purposes. These cups are typically made from materials such as paper, plastic, or foam, and are widely used in various sectors including food service, hospitality, and retail. The convenience and hygiene offered by disposable cups make them a popular choice for both consumers and businesses. They are commonly used in fast-food restaurants, coffee shops, and events where quick service and easy cleanup are essential. The market is driven by factors such as the increasing demand for on-the-go beverages, the rise in urbanization, and the growing awareness of hygiene and sanitation. Additionally, innovations in materials and design, such as biodegradable and compostable options, are influencing market trends as consumers and companies become more environmentally conscious. The market is also impacted by regulatory policies and consumer preferences, which vary across different regions. Overall, the Global Disposable Cups Market is a dynamic and evolving sector that reflects broader trends in consumer behavior and environmental awareness.

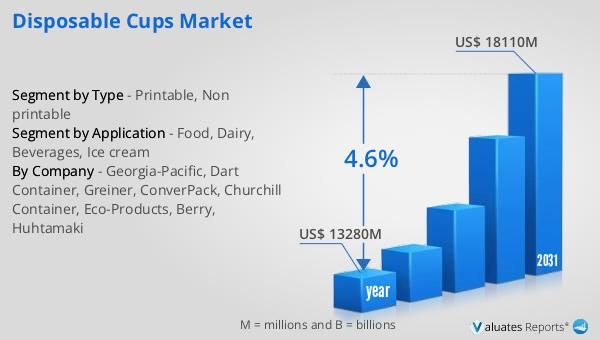
Disposable Cups Market

Printable, Non printable in the Global Disposable Cups Market:

In the Global Disposable Cups Market, products are often categorized based on their printability, which refers to the ability to print designs, logos, or information on the cups. Printable disposable cups are those that can be customized with various graphics, making them an effective marketing tool for businesses. These cups are commonly used by coffee shops, fast-food chains, and event organizers to promote their brand or convey messages to consumers. The printing process can involve different techniques such as flexographic, digital, or offset printing, each offering varying levels of quality and cost-effectiveness. Printable cups are typically made from materials that can withstand the printing process without compromising the cup's integrity or usability. On the other hand, non-printable disposable cups are those that do not support printing or customization. These cups are usually plain and are often used in situations where branding or messaging is not a priority. Non-printable cups are generally more cost-effective and are preferred by businesses that prioritize functionality over aesthetics. They are commonly used in settings such as hospitals, schools, and large-scale events where the focus is on practicality and efficiency. The choice between printable and non-printable cups depends on various factors including the intended use, budget, and marketing objectives of the business. In recent years, there has been a growing trend towards the use of eco-friendly materials in both printable and non-printable disposable cups. This shift is driven by increasing consumer awareness of environmental issues and the demand for sustainable products. Many companies are now offering biodegradable or compostable options that reduce the environmental impact of disposable cups. These eco-friendly alternatives are available in both printable and non-printable formats, allowing businesses to maintain their branding efforts while also addressing environmental concerns. The development of new materials and technologies continues to shape the Global Disposable Cups Market, offering businesses a wide range of options to meet their specific needs. As the market evolves, companies are likely to explore innovative ways to enhance the functionality and sustainability of disposable cups, further expanding the possibilities for both printable and non-printable products.

Food, Dairy, Beverages, Ice cream in the Global Disposable Cups Market:

The usage of disposable cups in the Global Disposable Cups Market spans across various sectors, including food, dairy, beverages, and ice cream. In the food industry, disposable cups are widely used for serving soups, salads, and other ready-to-eat meals. Their convenience and ease of use make them an ideal choice for takeout and delivery services, where quick service and minimal cleanup are essential. In the dairy sector, disposable cups are commonly used for packaging yogurt, milkshakes, and other dairy-based products. These cups provide a hygienic and convenient way to store and consume dairy products, especially in on-the-go scenarios. The beverage industry is one of the largest consumers of disposable cups, with coffee shops, juice bars, and fast-food chains relying heavily on them for serving hot and cold drinks. The demand for disposable cups in this sector is driven by the increasing popularity of takeaway beverages and the need for efficient service in busy environments. In the ice cream industry, disposable cups are used for serving single portions of ice cream, gelato, and frozen yogurt. These cups are designed to withstand low temperatures and prevent leaks, ensuring that the product remains fresh and enjoyable for consumers. The versatility and practicality of disposable cups make them a staple in these industries, catering to the diverse needs of consumers and businesses alike. As the Global Disposable Cups Market continues to grow, the demand for innovative and sustainable solutions is expected to rise, driving further advancements in the design and functionality of disposable cups.

Global Disposable Cups Market Outlook:

The global market for disposable cups was valued at approximately $13.28 billion in 2024, and it is anticipated to expand to a revised size of around $18.11 billion by 2031. This growth is expected to occur at a compound annual growth rate (CAGR) of 4.6% over the forecast period. The steady increase in market size reflects the rising demand for disposable cups across various sectors, driven by factors such as urbanization, changing consumer lifestyles, and the growing preference for convenience. As more people lead busy lives, the need for quick and easy solutions like disposable cups becomes more pronounced. Additionally, the market's growth is supported by innovations in materials and design, which cater to the increasing consumer awareness of environmental sustainability. Companies are investing in the development of eco-friendly disposable cups, such as those made from biodegradable or compostable materials, to meet the evolving preferences of environmentally conscious consumers. The market's expansion is also influenced by regional variations in consumer behavior and regulatory policies, which can impact the demand for disposable cups in different parts of the world. Overall, the Global Disposable Cups Market is poised for significant growth, driven by a combination of consumer trends, technological advancements, and environmental considerations.


Report Metric Details
Report Name Disposable Cups Market
Accounted market size in year US$ 13280 million
Forecasted market size in 2031 US$ 18110 million
CAGR 4.6%
Base Year year
Forecasted years 2025 - 2031
Segment by Type
  • Printable
  • Non printable
Segment by Application
  • Food
  • Dairy
  • Beverages
  • Ice cream
Consumption by Region
  • North America (United States, Canada)
  • Europe (Germany, France, UK, Italy, Russia)
  • Asia-Pacific (China, Japan, South Korea, Taiwan)
  • Southeast Asia (India)
  • Latin America (Mexico, Brazil)
By Company Georgia-Pacific, Dart Container, Greiner, ConverPack, Churchill Container, Eco-Products, Berry, Huhtamaki
Forecast units USD million in value
Report coverage Revenue and volume forecast, company share, competitive landscape, growth factors and trends

Global Empty Capsule Market Research Report 2025

What is Global Empty Capsule Market?

The Global Empty Capsule Market is a significant segment within the pharmaceutical and nutraceutical industries, focusing on the production and distribution of empty capsules used for encapsulating various substances. These capsules serve as a vital component in the delivery of medications, vitamins, and supplements, offering a convenient and efficient method for oral consumption. The market encompasses a wide range of capsule types, including gelatin and vegetarian-based capsules, catering to diverse consumer preferences and dietary restrictions. The demand for empty capsules is driven by the growing pharmaceutical industry, increasing health consciousness among consumers, and the rising popularity of dietary supplements. Additionally, advancements in capsule manufacturing technologies have led to the development of innovative capsule designs, enhancing their functionality and appeal. The market is characterized by a competitive landscape, with numerous manufacturers striving to offer high-quality, customizable capsule solutions to meet the evolving needs of their clients. As the global population continues to grow and age, the demand for pharmaceuticals and nutraceuticals is expected to rise, further propelling the expansion of the Global Empty Capsule Market. This market plays a crucial role in supporting the healthcare and wellness sectors by providing essential tools for effective drug delivery and nutritional supplementation.

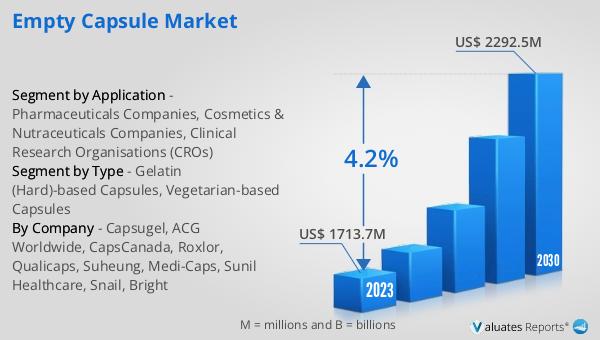
Empty Capsule Market

Gelatin (Hard)-based Capsules, Vegetarian-based Capsules in the Global Empty Capsule Market:

Gelatin (Hard)-based Capsules and Vegetarian-based Capsules are two primary types of capsules within the Global Empty Capsule Market, each offering unique benefits and applications. Gelatin capsules, traditionally made from animal-derived gelatin, are widely used due to their excellent film-forming properties, which ensure a robust and reliable encapsulation of active ingredients. These capsules are favored for their ability to dissolve quickly in the stomach, allowing for rapid release and absorption of the encapsulated substances. Gelatin capsules are particularly popular in the pharmaceutical industry for encapsulating drugs that require precise dosage and controlled release. However, the use of animal-derived gelatin has raised concerns among certain consumer groups, leading to the development and increasing popularity of vegetarian-based capsules. Vegetarian capsules are typically made from plant-derived materials such as hydroxypropyl methylcellulose (HPMC) or pullulan, offering a suitable alternative for individuals with dietary restrictions or ethical concerns regarding animal products. These capsules provide similar benefits to gelatin capsules, including excellent stability and compatibility with a wide range of substances. Vegetarian capsules are particularly favored in the nutraceutical and dietary supplement industries, where consumer demand for plant-based and vegan-friendly products is on the rise. The choice between gelatin and vegetarian capsules often depends on factors such as the nature of the encapsulated substance, target consumer preferences, and regulatory requirements. Manufacturers in the Global Empty Capsule Market continue to innovate and expand their product offerings to cater to the diverse needs of their clients, ensuring that both gelatin and vegetarian capsules remain integral components of the encapsulation industry. As consumer awareness and demand for transparency in product sourcing increase, the market for vegetarian capsules is expected to grow, providing a sustainable and ethical alternative to traditional gelatin capsules. This shift in consumer preferences is driving manufacturers to invest in research and development to enhance the performance and appeal of vegetarian capsules, ensuring they meet the rigorous standards of the pharmaceutical and nutraceutical industries. The Global Empty Capsule Market is poised for continued growth as it adapts to changing consumer demands and advances in encapsulation technology, offering a wide range of solutions to meet the diverse needs of the healthcare and wellness sectors.

Pharmaceuticals Companies, Cosmetics & Nutraceuticals Companies, Clinical Research Organisations (CROs) in the Global Empty Capsule Market:

The Global Empty Capsule Market finds extensive usage across various sectors, including Pharmaceuticals Companies, Cosmetics & Nutraceuticals Companies, and Clinical Research Organisations (CROs), each leveraging the unique benefits of empty capsules for their specific applications. In the pharmaceutical industry, empty capsules are a critical component in the formulation and delivery of medications. Pharmaceutical companies utilize these capsules to encapsulate active pharmaceutical ingredients (APIs), ensuring precise dosage and controlled release of drugs. The versatility of empty capsules allows for the encapsulation of a wide range of substances, including powders, granules, and even certain liquids, making them an essential tool in drug development and manufacturing. Additionally, the ability to customize capsules in terms of size, color, and imprinting provides pharmaceutical companies with the flexibility to differentiate their products and enhance brand recognition. In the cosmetics and nutraceuticals sectors, empty capsules are used to encapsulate vitamins, minerals, herbal extracts, and other dietary supplements, catering to the growing consumer demand for health and wellness products. These capsules offer a convenient and efficient method for delivering nutritional supplements, ensuring optimal absorption and bioavailability of the active ingredients. The use of vegetarian capsules in this sector is particularly noteworthy, as it aligns with the increasing consumer preference for plant-based and vegan-friendly products. Clinical Research Organisations (CROs) also rely on empty capsules for their research and development activities. CROs use these capsules to encapsulate investigational drugs and placebos for clinical trials, ensuring consistent and accurate dosing for study participants. The ability to produce customized capsules in small batches is particularly advantageous for CROs, as it allows for flexibility in trial design and rapid iteration of formulations. Overall, the Global Empty Capsule Market plays a vital role in supporting the pharmaceutical, cosmetics, and nutraceutical industries, providing essential tools for drug delivery, nutritional supplementation, and clinical research. As these industries continue to evolve and expand, the demand for high-quality, customizable empty capsules is expected to grow, driving innovation and development within the market.

Global Empty Capsule Market Outlook:

In 2024, the global market for empty capsules was valued at approximately $1,859 million. This market is anticipated to experience growth over the coming years, with projections indicating that it will reach an estimated size of $2,469 million by 2031. This growth trajectory represents a compound annual growth rate (CAGR) of 4.2% during the forecast period. The expansion of this market can be attributed to several factors, including the increasing demand for pharmaceuticals and dietary supplements, advancements in capsule manufacturing technologies, and the rising consumer preference for convenient and efficient drug delivery methods. As the global population continues to grow and age, the need for effective healthcare solutions is expected to rise, further driving the demand for empty capsules. Additionally, the growing awareness of health and wellness among consumers is fueling the demand for nutraceuticals and dietary supplements, contributing to the expansion of the empty capsule market. Manufacturers in this market are focusing on innovation and product development to meet the evolving needs of their clients, offering a wide range of capsule solutions that cater to diverse consumer preferences and regulatory requirements. The competitive landscape of the Global Empty Capsule Market is characterized by the presence of numerous manufacturers striving to offer high-quality, customizable capsule solutions. As the market continues to grow, manufacturers are investing in research and development to enhance the performance and appeal of their products, ensuring they meet the rigorous standards of the pharmaceutical and nutraceutical industries. The Global Empty Capsule Market is poised for continued growth as it adapts to changing consumer demands and advances in encapsulation technology, offering a wide range of solutions to meet the diverse needs of the healthcare and wellness sectors.


Report Metric Details
Report Name Empty Capsule Market
Accounted market size in year US$ 1859 million
Forecasted market size in 2031 US$ 2469 million
CAGR 4.2%
Base Year year
Forecasted years 2025 - 2031
Segment by Type
  • Gelatin (Hard)-based Capsules
  • Vegetarian-based Capsules
Segment by Application
  • Pharmaceuticals Companies
  • Cosmetics & Nutraceuticals Companies
  • Clinical Research Organisations (CROs)
Consumption by Region
  • North America (United States, Canada)
  • Europe (Germany, France, UK, Italy, Russia)
  • Asia-Pacific (China, Japan, South Korea, Taiwan)
  • Southeast Asia (India)
  • Latin America (Mexico, Brazil)
By Company Capsugel, ACG Worldwide, CapsCanada, Roxlor, Qualicaps, Suheung, Medi-Caps, Sunil Healthcare, Snail, Bright
Forecast units USD million in value
Report coverage Revenue and volume forecast, company share, competitive landscape, growth factors and trends

Global Sickle Cell Disease Drug Market Research Report 2025

What is Global Sickle Cell Disease Drug Market?

The Global Sickle Cell Disease Drug Market is a specialized segment within the broader pharmaceutical industry, focusing on the development and distribution of medications designed to treat sickle cell disease (SCD). Sickle cell disease is a genetic blood disorder characterized by the production of abnormal hemoglobin, leading to the distortion of red blood cells into a sickle shape. This condition can cause severe pain, frequent infections, and other serious health complications. The market for sickle cell disease drugs is driven by the increasing prevalence of the disease, particularly in regions such as Sub-Saharan Africa, India, the Middle East, and among certain ethnic groups in the United States and Europe. Advances in medical research and technology have led to the development of innovative treatments aimed at managing symptoms, reducing complications, and improving the quality of life for patients. The market includes a variety of drug types, such as hydroxyurea, L-glutamine, and newer gene therapies, each offering different mechanisms of action and benefits. As awareness of sickle cell disease grows and more effective treatments become available, the Global Sickle Cell Disease Drug Market is expected to expand, providing hope and improved outcomes for those affected by this challenging condition.

Sickle Cell Disease Drug Market

ARQ-092, BIVV-003, CAL-H, CTX-001, DRX-194, Others in the Global Sickle Cell Disease Drug Market:

ARQ-092, BIVV-003, CAL-H, CTX-001, DRX-194, and other emerging therapies represent a new frontier in the treatment of sickle cell disease, each offering unique approaches to managing this complex condition. ARQ-092 is an investigational drug that targets the AKT pathway, which is involved in cell survival and proliferation. By inhibiting this pathway, ARQ-092 aims to reduce the sickling of red blood cells and alleviate the symptoms associated with sickle cell disease. BIVV-003, on the other hand, is a gene-editing therapy that utilizes CRISPR technology to modify the patient's own hematopoietic stem cells. This approach seeks to correct the genetic mutation responsible for sickle cell disease, offering the potential for a long-term cure. CAL-H is another gene therapy in development, focusing on the delivery of a functional copy of the beta-globin gene to the patient's stem cells. This therapy aims to increase the production of normal hemoglobin, thereby reducing the sickling of red blood cells. CTX-001 is a promising gene-editing therapy that also employs CRISPR technology to modify the patient's stem cells. By reactivating the production of fetal hemoglobin, CTX-001 seeks to prevent the sickling of red blood cells and alleviate the symptoms of sickle cell disease. DRX-194 is a small molecule drug that targets the underlying causes of sickle cell disease by modulating the expression of specific genes involved in red blood cell production. This approach aims to increase the production of healthy red blood cells and reduce the complications associated with the disease. In addition to these therapies, there are several other drugs in development that target different aspects of sickle cell disease, such as pain management, inflammation reduction, and prevention of vaso-occlusive crises. The development of these innovative therapies reflects the growing understanding of the molecular mechanisms underlying sickle cell disease and the commitment of researchers and pharmaceutical companies to improving the lives of patients. As these therapies progress through clinical trials and receive regulatory approval, they have the potential to transform the treatment landscape for sickle cell disease, offering new hope to patients and their families.

Hospital, Clinic, Others in the Global Sickle Cell Disease Drug Market:

The usage of drugs from the Global Sickle Cell Disease Drug Market is crucial in various healthcare settings, including hospitals, clinics, and other medical facilities. In hospitals, these drugs are often administered to patients experiencing severe complications of sickle cell disease, such as acute pain crises, infections, or organ damage. Hospital settings provide the necessary infrastructure for the administration of intravenous therapies and the monitoring of patients for potential side effects. In addition, hospitals often serve as centers for clinical trials, where new therapies are tested and evaluated for safety and efficacy. Clinics, on the other hand, play a vital role in the ongoing management of sickle cell disease. Patients visit clinics for regular check-ups, monitoring of their condition, and adjustments to their treatment regimen. Clinics provide a more accessible and less intensive setting for the administration of oral medications and other therapies that do not require hospitalization. They also offer educational resources and support services to help patients manage their condition and improve their quality of life. Other healthcare settings, such as community health centers and specialized sickle cell disease treatment centers, also play a significant role in the management of the disease. These facilities often focus on providing comprehensive care, including genetic counseling, psychological support, and social services, to address the multifaceted needs of patients and their families. The availability and accessibility of sickle cell disease drugs in these various settings are essential for ensuring that patients receive timely and effective treatment. As new therapies become available, healthcare providers must stay informed about the latest developments in the field and incorporate these advancements into their practice. This requires ongoing education and collaboration among healthcare professionals, researchers, and pharmaceutical companies to ensure that patients receive the best possible care. The integration of innovative therapies into the treatment of sickle cell disease has the potential to significantly improve patient outcomes and reduce the burden of the disease on individuals and healthcare systems.

Global Sickle Cell Disease Drug Market Outlook:

The global pharmaceutical market was valued at approximately 1,475 billion USD in 2022, with an anticipated growth rate of 5% annually over the next six years. This growth is indicative of the increasing demand for pharmaceutical products worldwide, driven by factors such as an aging population, rising prevalence of chronic diseases, and advancements in medical technology. In comparison, the chemical drug market, a subset of the broader pharmaceutical industry, has also shown significant growth. It was estimated to have increased from 1,005 billion USD in 2018 to 1,094 billion USD in 2022. This growth reflects the ongoing development and commercialization of new chemical entities and the expansion of existing drug portfolios. The chemical drug market encompasses a wide range of products, including small molecule drugs, which are typically synthesized through chemical processes. These drugs play a crucial role in the treatment of various medical conditions, from infectious diseases to cancer and cardiovascular disorders. The growth of the chemical drug market is supported by continuous research and development efforts, as well as strategic partnerships and collaborations among pharmaceutical companies. As the demand for effective and innovative treatments continues to rise, the chemical drug market is expected to remain a vital component of the global pharmaceutical industry. The expansion of both the pharmaceutical and chemical drug markets underscores the importance of ongoing investment in research and development, as well as the need for regulatory frameworks that support the safe and efficient delivery of new therapies to patients.


Report Metric Details
Report Name Sickle Cell Disease Drug Market
CAGR 5%
Segment by Type
  • ARQ-092
  • BIVV-003
  • CAL-H
  • CTX-001
  • DRX-194
  • Others
Segment by Application
  • Hospital
  • Clinic
  • Others
Consumption by Region
  • North America (United States, Canada)
  • Europe (Germany, France, UK, Italy, Russia)
  • Asia-Pacific (China, Japan, South Korea, Taiwan)
  • Southeast Asia (India)
  • Latin America (Mexico, Brazil)
By Company Acceleron Pharma Inc, Addmedica SAS, Angiocrine Bioscience Inc, Annexin Pharmaceuticals AB, ArQule Inc, Bio Products Laboratory Ltd, Bioverativ Inc, bluebird bio Inc, Bristol-Myers Squibb Co, Calimmune Inc, CRISPR Therapeutics, CSL Ltd, Daiichi Sankyo Co Ltd, Editas Medicine Inc, Errant Gene Therapeutics LLC, Gamida Cell Ltd, Genethon SA, Gilead Sciences Inc, Global Blood Therapeutics Inc
Forecast units USD million in value
Report coverage Revenue and volume forecast, company share, competitive landscape, growth factors and trends

Global Actinic (Solar) Keratosis Treatment Market Research Report 2025

What is Global Actinic (Solar) Keratosis Treatment Market?

The Global Actinic (Solar) Keratosis Treatment Market refers to the industry focused on developing and providing treatments for actinic keratosis, a skin condition caused by prolonged exposure to ultraviolet (UV) rays from the sun. This condition is characterized by rough, scaly patches on the skin, primarily affecting areas frequently exposed to the sun, such as the face, ears, neck, scalp, and hands. Actinic keratosis is considered a precancerous condition, as it can potentially progress to squamous cell carcinoma, a type of skin cancer, if left untreated. The market for actinic keratosis treatment includes a variety of therapeutic options, such as topical medications, cryotherapy, photodynamic therapy, and surgical procedures. The increasing awareness of skin cancer risks, coupled with the growing prevalence of actinic keratosis due to rising sun exposure and aging populations, drives the demand for effective treatments. Additionally, advancements in dermatological research and technology contribute to the development of innovative therapies, further expanding the market. As a result, the Global Actinic (Solar) Keratosis Treatment Market plays a crucial role in addressing the healthcare needs of individuals affected by this common skin condition.

Actinic (Solar) Keratosis Treatment Market

854-A, ACT-01, AD-17137, Celecoxib, DFD-08, GDC-695, Others in the Global Actinic (Solar) Keratosis Treatment Market:

The Global Actinic (Solar) Keratosis Treatment Market encompasses a range of therapeutic agents, including 854-A, ACT-01, AD-17137, Celecoxib, DFD-08, GDC-695, and others, each contributing uniquely to the management of actinic keratosis. 854-A is a promising compound under investigation, known for its potential to target specific pathways involved in the development of actinic keratosis lesions. This compound aims to provide a targeted approach, minimizing damage to surrounding healthy tissues. ACT-01, another innovative treatment, focuses on modulating the immune response to enhance the body's ability to combat precancerous cells. By boosting the immune system's activity, ACT-01 offers a novel mechanism for addressing actinic keratosis. AD-17137 is a topical formulation designed to penetrate the skin effectively, delivering active ingredients directly to the affected areas. This targeted delivery system enhances the efficacy of the treatment while reducing systemic side effects. Celecoxib, a well-known nonsteroidal anti-inflammatory drug (NSAID), has shown potential in reducing the risk of actinic keratosis progression. Its anti-inflammatory properties help alleviate the symptoms associated with the condition, providing relief to patients. DFD-08 is a topical gel formulation that combines multiple active ingredients to address actinic keratosis comprehensively. This multi-faceted approach targets different aspects of the condition, offering a holistic treatment option. GDC-695, a novel agent, is being explored for its ability to inhibit specific enzymes involved in the proliferation of precancerous cells. By targeting these enzymes, GDC-695 aims to prevent the progression of actinic keratosis to more severe forms of skin cancer. In addition to these specific treatments, the market also includes other therapeutic options, such as cryotherapy, photodynamic therapy, and surgical interventions. Cryotherapy involves freezing the affected skin cells, effectively destroying them and preventing further progression. Photodynamic therapy utilizes light-activated compounds to selectively target and destroy precancerous cells, offering a non-invasive treatment option. Surgical procedures, such as curettage and excision, are employed for more advanced cases, where lesions are removed to prevent cancerous transformation. The diverse range of treatments available in the Global Actinic (Solar) Keratosis Treatment Market reflects the complexity of the condition and the need for tailored approaches to meet individual patient needs. As research continues to advance, these treatments hold the potential to improve patient outcomes and reduce the burden of actinic keratosis on individuals and healthcare systems worldwide.

Hospital, Clinic, Others in the Global Actinic (Solar) Keratosis Treatment Market:

The usage of the Global Actinic (Solar) Keratosis Treatment Market spans various healthcare settings, including hospitals, clinics, and other medical facilities, each playing a vital role in managing this prevalent skin condition. In hospitals, the treatment of actinic keratosis often involves a multidisciplinary approach, where dermatologists, oncologists, and other specialists collaborate to provide comprehensive care. Hospitals are equipped with advanced diagnostic tools and treatment technologies, enabling precise assessment and intervention for patients with actinic keratosis. In this setting, patients may undergo procedures such as cryotherapy, photodynamic therapy, or surgical excision, depending on the severity and extent of their condition. The hospital environment also facilitates the management of complex cases, where patients may require a combination of treatments to achieve optimal outcomes. Clinics, on the other hand, offer a more accessible and convenient option for patients seeking treatment for actinic keratosis. Dermatology clinics, in particular, specialize in skin conditions and provide targeted therapies tailored to individual patient needs. In these settings, patients can receive topical treatments, such as AD-17137 or DFD-08, which are applied directly to the affected areas. Clinics also offer follow-up care and monitoring, ensuring that patients receive ongoing support and adjustments to their treatment plans as needed. The personalized approach in clinics allows for early intervention and management of actinic keratosis, reducing the risk of progression to more severe forms of skin cancer. Beyond hospitals and clinics, other healthcare facilities, such as outpatient centers and specialized dermatology practices, contribute to the treatment landscape for actinic keratosis. These facilities often focus on preventive care and education, raising awareness about the importance of sun protection and regular skin checks. By promoting early detection and intervention, these settings play a crucial role in reducing the incidence and impact of actinic keratosis. Additionally, telemedicine platforms have emerged as valuable tools in the management of actinic keratosis, allowing patients to consult with healthcare providers remotely and receive guidance on treatment options. This approach enhances accessibility to care, particularly for individuals in remote or underserved areas. Overall, the Global Actinic (Solar) Keratosis Treatment Market's presence in hospitals, clinics, and other healthcare settings underscores the importance of a comprehensive and coordinated approach to managing this common skin condition. By leveraging the strengths of each setting, healthcare providers can deliver effective and timely interventions, improving patient outcomes and quality of life.

Global Actinic (Solar) Keratosis Treatment Market Outlook:

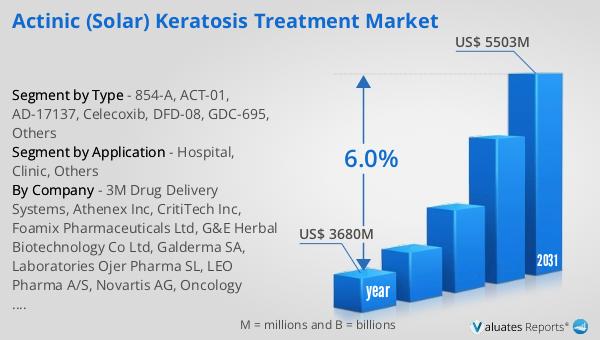
In 2024, the global market for Actinic Solar Keratosis Treatment was valued at approximately $3.68 billion. It is anticipated to grow significantly, reaching an estimated size of $5.503 billion by 2031, with a compound annual growth rate (CAGR) of 6.0% throughout the forecast period. In the broader context, the global pharmaceutical market was valued at $1.475 trillion in 2022, with an expected growth rate of 5% over the next six years. Comparatively, the chemical drug market has shown an increase from $1.005 trillion in 2018 to $1.094 trillion in 2022. This data highlights the robust growth potential within the Actinic Solar Keratosis Treatment Market, driven by increasing awareness of skin health and the rising prevalence of actinic keratosis. The market's expansion is supported by advancements in dermatological research and the development of innovative treatment options. As the demand for effective therapies continues to rise, the Actinic Solar Keratosis Treatment Market is poised to play a crucial role in addressing the healthcare needs of individuals affected by this condition. The projected growth reflects the market's capacity to adapt to evolving patient needs and technological advancements, ensuring improved outcomes for those seeking treatment for actinic keratosis.


Report Metric Details
Report Name Actinic (Solar) Keratosis Treatment Market
Accounted market size in year US$ 3680 million
Forecasted market size in 2031 US$ 5503 million
CAGR 6.0%
Base Year year
Forecasted years 2025 - 2031
Segment by Type
  • 854-A
  • ACT-01
  • AD-17137
  • Celecoxib
  • DFD-08
  • GDC-695
  • Others
Segment by Application
  • Hospital
  • Clinic
  • Others
By Region
  • North America (United States, Canada)
  • Europe (Germany, France, UK, Italy, Russia) Rest of Europe
  • Nordic Countries
  • Asia-Pacific (China, Japan, South Korea)
  • Southeast Asia (India, Australia)
  • Rest of Asia
  • Latin America (Mexico, Brazil)
  • Rest of Latin America
  • Middle East & Africa (Turkey, Saudi Arabia, UAE, Rest of MEA)
By Company 3M Drug Delivery Systems, Athenex Inc, CritiTech Inc, Foamix Pharmaceuticals Ltd, G&E Herbal Biotechnology Co Ltd, Galderma SA, Laboratories Ojer Pharma SL, LEO Pharma A/S, Novartis AG, Oncology Research International Ltd, Promius Pharma LLC, Valeant Pharmaceuticals International Inc, Vectura Group Plc
Forecast units USD million in value
Report coverage Revenue and volume forecast, company share, competitive landscape, growth factors and trends

Global Strong Cation Exchange Agarose Gel Market Research Report 2025

What is Global Strong Cation Exchange Agarose Gel Market? The Global Strong Cation Exchange Agarose Gel Market is a specialized segment wit...